
Cliff Asness on Diversification: The Real Risk Investors Miss
Monday, April 13, 2026 · Johnny Hopkins
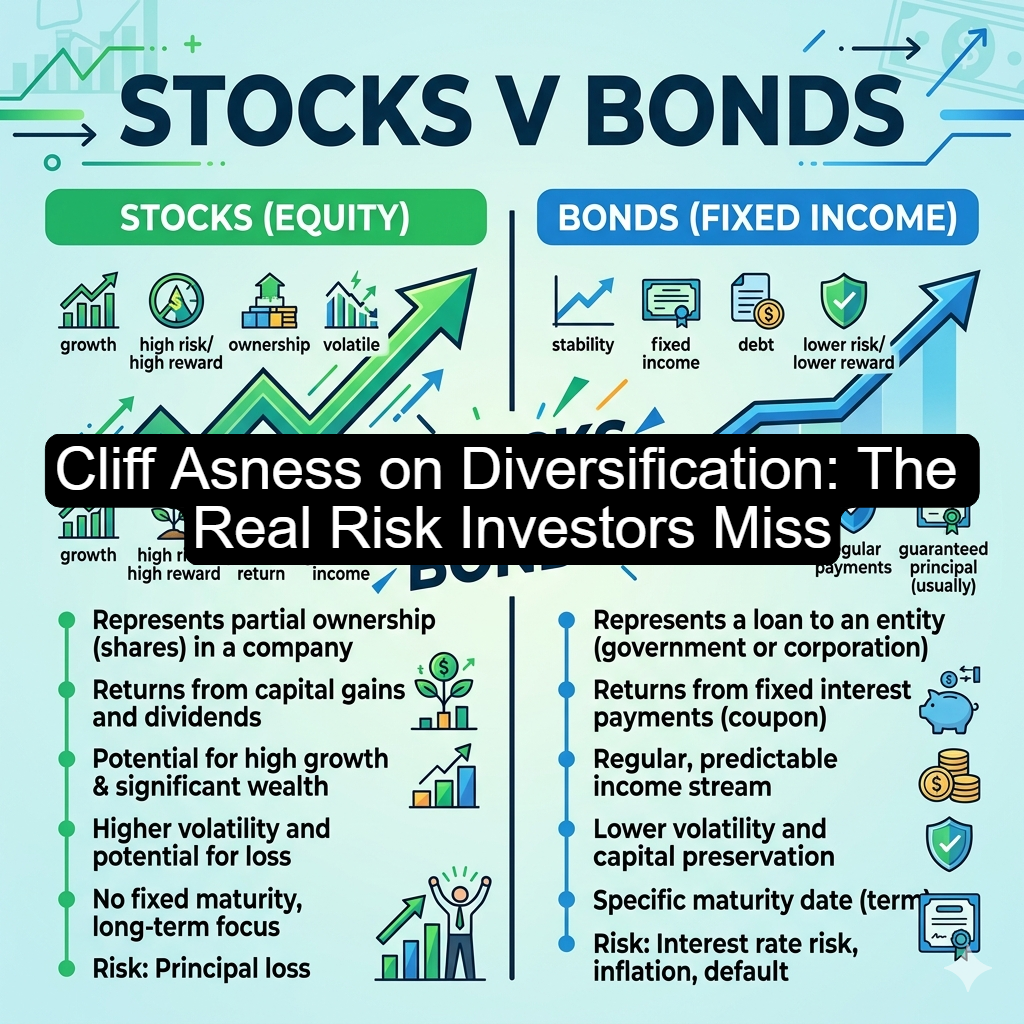
Markets have a habit of taking a real issue and turning it into a fashionable excuse. The recent positive stock-bond correlation has become one of those excuses, often used to justify replacing bonds with whatever happens to be selling well.
In their latest report, Cliff Asness and colleagues reject that leap with refreshing force. They write, “Unfortunately, many investors, armed with dubious advice, are doing the opposite of what they should be.”
That matters because correlation alone does not erase the job bonds can still perform inside a portfolio. The more basic problem is that many allocations were already dominated by equities long before bond behavior changed.
As the report notes, “The current environment is indeed different from the past in many ways. But the assertion that a positive stock-bond correlation means investor portfolios are now facing a diversification problem is incomplete: they are now, and always have been, facing a diversification problem.”
In plain terms, investors may be diagnosing the wrong disease. If stocks remain the main driver of gains and losses, then swapping bonds for assets carrying even more equity sensitivity can worsen the condition.
That is why the authors are blunt about several popular substitutes. On private credit, they conclude: “If you like the asset class, fine; but if you’re looking for new sources of diversification, this ain’t it.”
They are equally skeptical of packaged equity products sold as safer replacements for bonds. “Bottom-line: an equity beta three times that of bonds isn’t a great contender for solving a diversification problem.”
Investors should pause on that sentence. Many strategies promise smoother rides, but if the engine under the hood is still equity exposure, the destination may not be very different.
The sharpest criticism is reserved for crypto allocations marketed as ballast. “Investors moving from bonds to Bitcoin for diversification reasons are getting 10x the equity risk for every dollar they move.”
Whether one likes digital assets or not is beside the point. The issue is portfolio role, not cultural preference.
So what should replace weak diversification? The answer is not novelty; it is actual diversifiers. The report highlights approaches such as market neutral and trend-following because their return streams have behaved differently from broad equities. Those strategies are not magic, and manager selection still matters, but at least they address the stated objective.
The closing takeaway is the one investors should keep pinned to the desk: “investors who believe that bonds are impaired because of correlation should apply a high diversification bar for the next asset they bring into their portfolio.”
That is the standard worth using in any cycle. Not what is exciting, not what had a strong trailing run, and not what comes wrapped in polished marketing language. Real diversification should be measured by behavior when pressure arrives, not by the sales pitch that came before it.
Full report here:
A Positive Stock-Bond Correlation Is a Terrible Reason to Add More Equity Risk to Your Portfolio
 Cliff Asness: “We See An Attractive Market For What We Do”
 Where Is the Deep Value in Small and Micro Caps This Week?
 AI Stock Market Bubble: Can the Technology Succeed While Stocks Crash?