
Bill Ackman Says It’s a “Very Good Time” to Put Capital to Work
Wednesday, April 29, 2026 · Johnny Hopkins
Seasoned investors are increasingly leaning into a setup where uncertainty coexists with what they see as unusually attractive valuations. During his recent interview with Bloomberg, Bill Ackman captured that dynamic directly, noting that “we think it’s a very good time to put the capital to work, and we invest in the most liquid companies in the world. So it’s really it’s weeks, not months.”
That urgency reflects a broader conviction forming beneath the surface of headline indices. While benchmarks suggest resilience, Ackman points to a disconnect between price and intrinsic value, noting, “some of the best businesses in the world are trading at the lowest multiples. They’ve traded at, in some cases, in history.”
This framing challenges the notion that markets are broadly expensive, instead highlighting pockets of deep opportunity within high-quality names.
Importantly, Ackman does not characterize this as a fleeting anomaly but as part of a broader cyclical reset.
He observed that “those multiples bottomed maybe two weeks ago, so we’re a little bit off the the all time bottom, but, you know, very bullish on the economy.”
That statement suggests the easy gains from panic-level pricing may have passed, yet the forward return profile remains attractive.
His perspective also underscores the importance of time horizon. In a market dominated by short-term flows and algorithmic positioning, Ackman highlighted structural volatility: “there’s so much capital leveraged, short term focused, tightly risk managed, which means stop losses and things like this.”
The implication is that forced selling and technical dislocations continue to create entry points for patient capital.
Indeed, Ackman’s framework for opportunity hinges on this mismatch. He explained that “once in a while, you know, the price of a really high quality company gets stupidly cheap because someone gets you know, is forced to sell because of a bad print for the quarter or a guidance change.”
These episodic distortions, rather than macro timing, form the backbone of his strategy.
While he concedes that the absolute trough may be behind us—“I would say we’re above stupidly cheap bottom”—he remains constructive, adding that “it’s still a very high rate of projected return for some of the best businesses in the world.”
That nuance matters. The narrative is no longer about distressed pricing but about sustained mispricing relative to long-term earnings power.
On the macro front, Ackman’s outlook reinforces the bullish case. He stated, “I think we’re heading into a very good place,” pointing to easing geopolitical pressures, potential rate cuts, and strong investment trends.
Combined with ongoing capital deployment in areas like AI and energy, the setup suggests a supportive environment for equities.
Taken together, these remarks frame a market that rewards selectivity over broad exposure. For investors willing to look past index-level noise and focus on business fundamentals, the message is clear: the opportunity set remains compelling, even if the most dramatic bargains have already been claimed.
Full interview here:
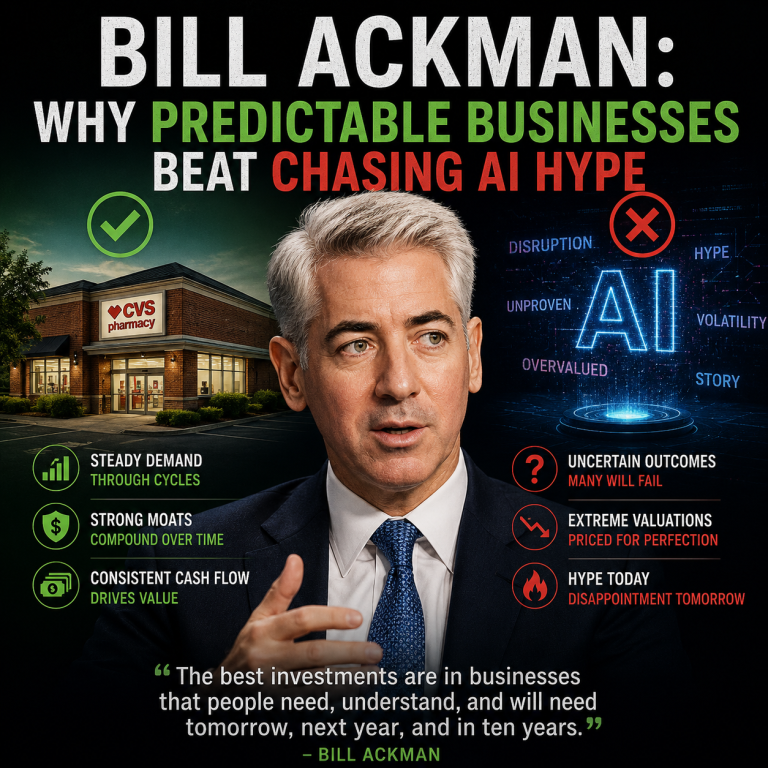 Bill Ackman: Why Predictable Businesses Beat Chasing AI Hype
 Where Are the Highest-Quality Value Opportunities This Week?
 AI Spending Boom: Are Big Tech Companies Taking on Too Much Debt?