
Equinor ASA (EQNR): Undervalued European Energy Company
Wednesday, August 26, 2026 · Johnny Hopkins
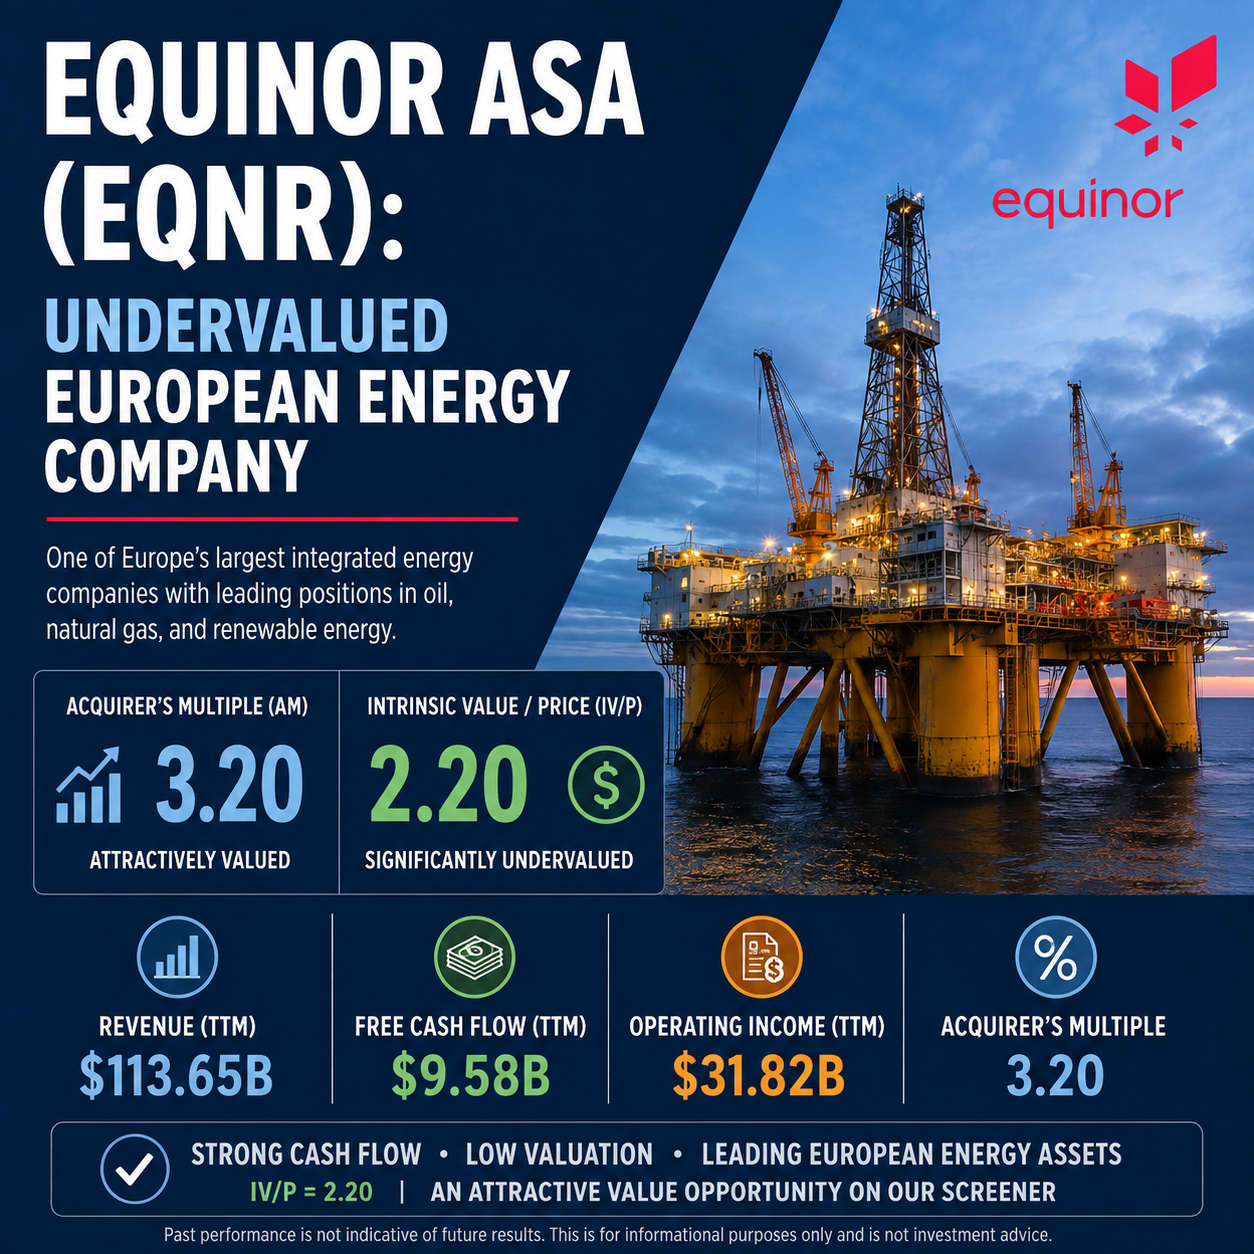
As part of our ongoing series at The Acquirer’s Multiple, each week we highlight a stock from our Stock Screeners that may represent an undervalued opportunity hiding in plain sight.
This week’s spotlight is Equinor ASA (EQNR) — one of Europe’s largest energy companies, with major operations across oil, natural gas, offshore production, and renewable energy.
Despite commodity-price uncertainty and the cyclical nature of energy markets, Equinor currently trades at valuation levels that suggest investors may be overlooking its substantial earnings and cash flow generation.
Business Overview
Equinor is a Norway-based integrated energy company with operations spanning:
✓ Oil and natural gas exploration and production
✓ Offshore energy production
✓ Natural gas supply and trading
✓ Refining and marketing
✓ Offshore wind and renewable energy
The company is particularly important to European energy markets and remains a major supplier of natural gas to Europe.
What Is IV/P (Intrinsic Value to Price)?
IV/P compares a conservative intrinsic valuation to the current market price.
IV/P > 1 → Undervalued
IV/P < 1 → Overvalued
EQNR’s IV/P = 2.20, suggesting the stock may be trading significantly below conservative intrinsic value estimates.
Supporting Metrics (Currency in USD)
Revenue (TTM): ≈ $113.65B
Operating Income (TTM): ≈ $31.82B
Net Income (TTM): ≈ $9.06B
Free Cash Flow (TTM): ≈ $9.58B
Acquirer’s Multiple (AM): 3.20
An Acquirer’s Multiple of just 3.20 places Equinor among the attractively valued companies currently appearing on our Screener.
Revenue & Profitability
Equinor continues to generate substantial profits despite energy prices normalizing from the exceptional levels experienced during the European energy crisis.
TTM operating income stands at approximately $31.82 billion, while net income is approximately $9.06 billion.
The company’s scale, low-cost offshore assets, and significant European natural gas exposure continue to underpin profitability.
Balance Sheet & Cash Flow
From the latest reported balance sheet:
Total Assets: ≈ $131.73B
Total Liabilities: ≈ $91.23B
Total Equity: ≈ $40.50B
Total Debt: ≈ $31.22B
Net Debt: ≈ $22.77B
Operating Cash Flow (TTM): ≈ $23.14B
Free Cash Flow (TTM): ≈ $9.58B
Equinor continues to generate substantial operating cash flow while maintaining a manageable balance sheet.
Why EQNR May Be Attractive
Key risks include lower oil and natural gas prices, geopolitical uncertainty, energy-transition spending, and the inherent cyclicality of commodity markets.
However, Equinor combines more than $113 billion in TTM revenue, strong operating cash flow, significant European energy assets, an Acquirer’s Multiple of 3.20, and an IV/P of 2.20.
Conclusion
With an IV/P of 2.20 and an Acquirer’s Multiple of just 3.20, Equinor screens as an interesting value opportunity currently appearing on our Screener.
Its enormous energy asset base, strong cash generation, strategic position in European natural gas, and low valuation make EQNR worthy of further research.