
Embecta Corp. (EMBC): Deeply Undervalued Global Medical Device Company
Wednesday, August 5, 2026 · Johnny Hopkins
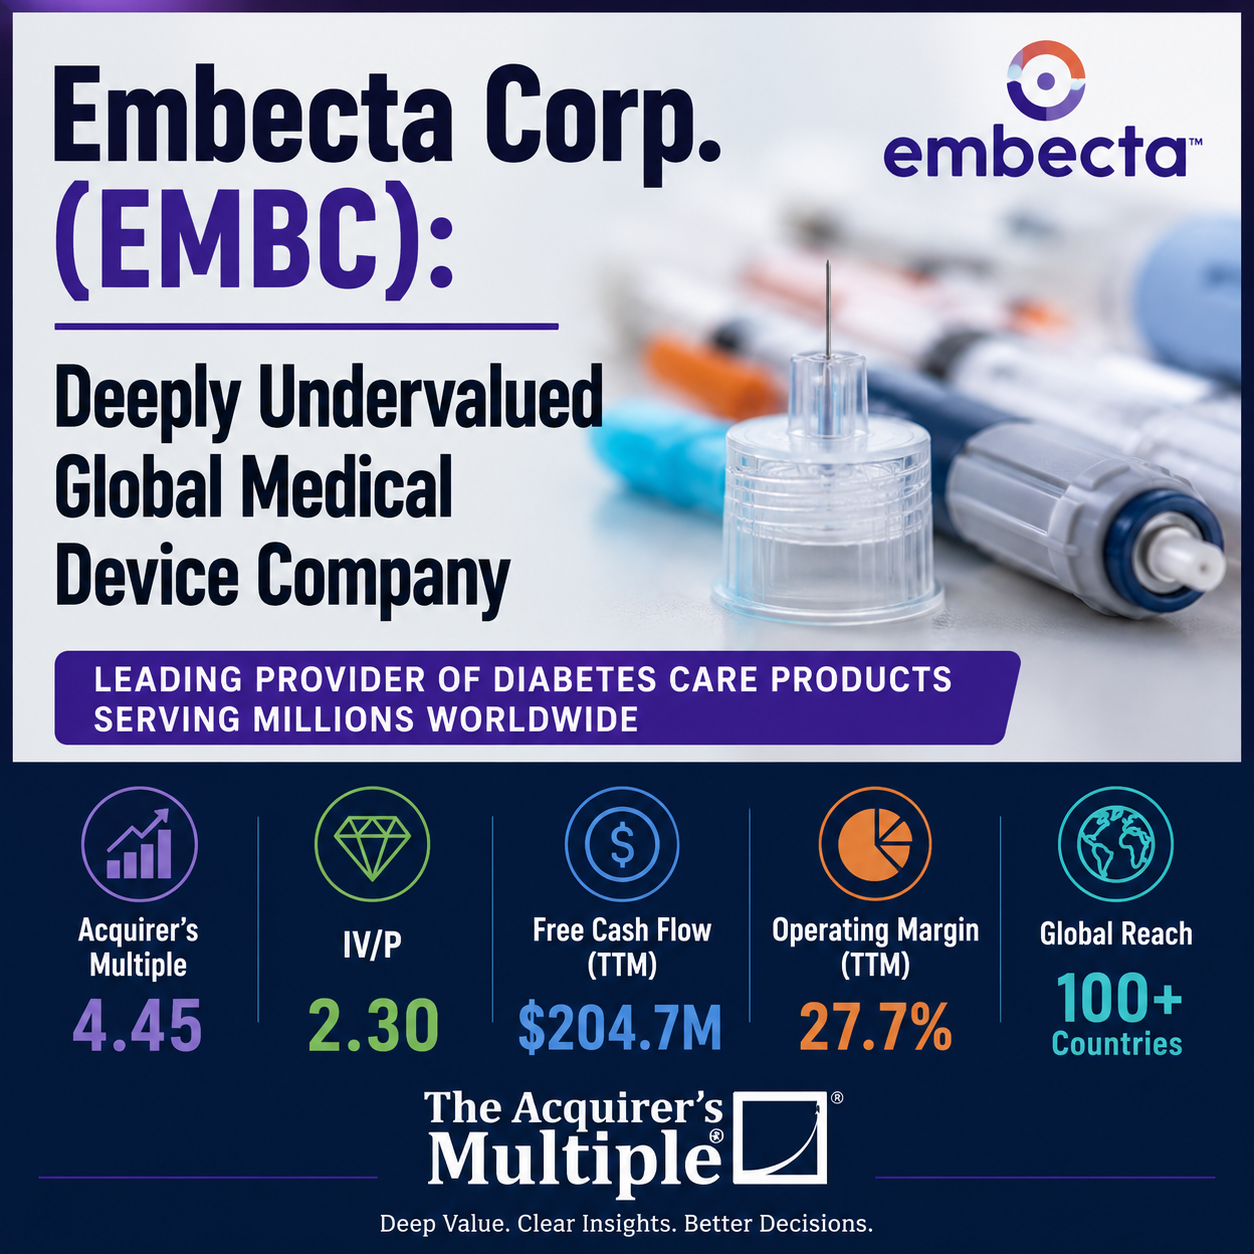
As part of our ongoing series at The Acquirer’s Multiple, each week we highlight a stock from our Stock Screeners that may represent an undervalued opportunity hiding in plain sight.
This week’s spotlight is Embecta Corp. (EMBC) — a global medical device company focused on diabetes care. Following its separation from Becton, Dickinson and Company, Embecta has become one of the world’s largest pure-play diabetes management businesses, providing insulin delivery products to millions of people across more than 100 countries.
Despite operating in the defensive healthcare sector with stable recurring demand, EMBC currently trades at valuation levels that may suggest investors are overlooking its strong cash generation, resilient profitability, and improving balance sheet.
Business Overview
Embecta develops, manufactures, and markets medical devices designed for people living with diabetes.
Core components of the business include:
✓ Insulin pen needles
✓ Insulin syringes
✓ Diabetes care products
✓ Global manufacturing and distribution
✓ Ongoing product innovation
The company’s leading market position, trusted brand, and extensive global distribution network provide meaningful competitive advantages within the diabetes care market.
What Is IV/P (Intrinsic Value to Price)?
IV/P compares a conservative intrinsic valuation to the current market price.
IV/P > 1 → Undervalued
IV/P < 1 → Overvalued
EMBC’s IV/P = 2.30, suggesting the stock may be trading well below conservative intrinsic value estimates.
Supporting Metrics (Currency in USD)
Revenue (TTM): ≈ $1.04B
Operating Income (TTM): ≈ $288.5M
Net Income (TTM): ≈ $111.9M
Free Cash Flow (TTM): ≈ $204.7M
Acquirer’s Multiple (AM): 4.45
An Acquirer’s Multiple of just 4.45 places EMBC among the most attractively valued companies currently appearing on our Screener.
Revenue & Profitability
Embecta continues to generate strong profitability despite modest revenue declines following its spin-off, supported by disciplined cost management and the recurring nature of diabetes care products.
Approximate margins:
Gross Margin ≈ 62.0%
Operating Margin ≈ 27.7%
Pre-Tax Margin ≈ 16.3%
Net Margin ≈ 10.8%
These results reflect the company’s high-margin product portfolio, operational efficiency, and strong market position in insulin delivery devices.
Balance Sheet & Cash Flow
From the balance sheet:
Total Assets: ≈ $1.09B
Total Liabilities: ≈ $1.74B
Shareholders’ Equity: Negative (≈ -$651M)
Net Debt: ≈ $1.17B
Operating Cash Flow (TTM): ≈ $213.5M
Free Cash Flow (TTM): ≈ $204.7M
While the company carries a meaningful debt load following its separation from BD, Embecta continues to generate robust operating cash flow and free cash flow that support ongoing debt reduction, dividend payments, and investment in the business.
This cash generation supports:
✓ Debt repayment
✓ Dividend payments
✓ Product innovation
✓ Operational flexibility
Why EMBC May Be Attractive
Market concerns include:
• Elevated debt levels
• Limited top-line growth
• Competitive pressures within diabetes care
• Pricing and reimbursement risks
However, fundamentals remain compelling:
• Acquirer’s Multiple of 4.45 indicates an attractive valuation
• IV/P of 2.30 suggests shares trade well below intrinsic value
• Strong recurring revenue base
• High operating margins
• Excellent free cash flow generation
• Stable demand driven by diabetes treatment
Conclusion
With an IV/P of 2.30 and an Acquirer’s Multiple of 4.45, Embecta screens as one of the more compelling value opportunities currently appearing on our Screener.
Although investors remain focused on the company’s leverage and modest growth profile, Embecta continues to generate substantial cash flow from a highly recurring business serving a large and growing global diabetes population. For value investors seeking a profitable healthcare company trading at a significant discount to conservative intrinsic value estimates, EMBC may warrant closer attention.