
Jeremy Grantham: Market Hype Can Overpower Fundamentals—But Not Forever
Sunday, July 12, 2026 · Johnny Hopkins
Investor enthusiasm has once again pushed valuations into territory where fundamentals appear increasingly secondary to narratives, momentum, and the fear of missing out. For Jeremy Grantham, the current environment carries familiar characteristics of previous speculative periods, when rising prices themselves became the primary justification for buying.
Reflecting on the difficulty of maintaining investment discipline during powerful bull markets, Grantham acknowledges the pressure facing professional investors. “By the end of all this, I realized that if you’re a big firm with stockholders and all that good stuff, you can’t fight a bull market. Keynes was right. He nailed it. … The stocks are going up—you recommend them.”
That dynamic becomes particularly dangerous when investor enthusiasm combines with compelling stories about technological transformation. Grantham points to the extraordinary valuations being attached to companies promising enormous future opportunities from artificial intelligence, despite considerable uncertainty surrounding their eventual profitability.
“So supply and demand being what it is, it’s hard to imagine the price won’t go up, and perhaps it will go up a lot. And in the end, the reality will come out, and this will turn out to be, of course, one of the landmark historical events that I so value in history looking back.”
The challenge for investors is that speculative assets can continue rising far longer than valuation models might suggest. Momentum can overwhelm fundamentals for extended periods, rewarding buyers who ignore traditional measures of intrinsic value and punishing those who remain disciplined.
Grantham’s approach remains grounded in a simple principle: price eventually matters.
“I only recognize that it’s much cheaper, and if I buy and hold it forever, and if it’s cheaper, I will make more money, and that happens to be a mathematical fact. In the short term, however, the valueless company like a meme stock, can outperform and go up 20 times. It doesn’t change the long-term value, and eventually it will go back down again.”
That distinction between short-term price movements and long-term value may be increasingly important in today’s market. Investors are once again being asked to believe that extraordinary technological developments justify extraordinary valuations, while history suggests that even genuine innovation does not guarantee attractive investment returns when purchased at excessive prices.
Grantham’s concern is not that prices cannot continue higher. In fact, speculative markets often become most dangerous precisely because they can continue rewarding investors long after valuations have detached from fundamentals.
The question facing investors is therefore not whether enthusiasm can push prices higher, but how much future optimism has already been reflected in current valuations. History repeatedly demonstrates that compelling narratives, abundant capital, and accelerating momentum can sustain speculative excess for years. It also demonstrates that eventually, fundamentals regain their influence.
For disciplined investors, patience may prove increasingly difficult. It may also prove increasingly valuable.
Full interview here:
Jeremy Grantham: ‘Almost Everything Looks More Attractive Than the US Equity Market’ (Long View)
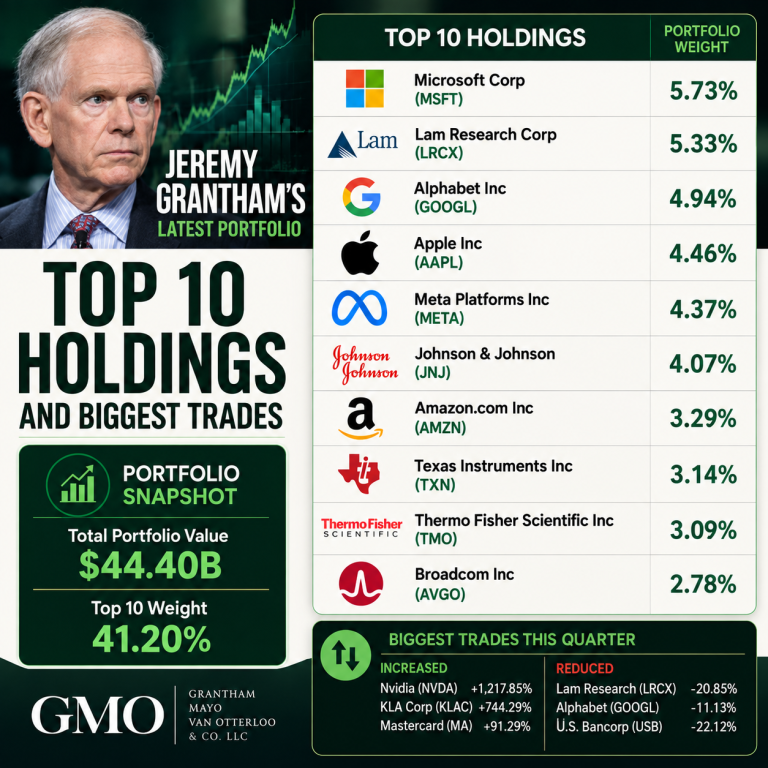 Jeremy Grantham’s Latest Portfolio: Top 10 Holdings & Biggest Trades
 Where Is the Deep Value in Small and Micro Caps This Week?
 AI Stock Market Bubble: Can the Technology Succeed While Stocks Crash?