
Jeremy Grantham: Fast Forward A Few Years, Everybody Is Doing AI, Aren’t They?
Monday, May 18, 2026 · Johnny Hopkins
Artificial intelligence spending, concentrated market leadership, and relentless momentum in mega-cap technology stocks continue to dominate investor attention. ‘
The belief that a handful of companies can sustain elevated growth and profitability indefinitely has pushed valuations higher, even as broader concerns surrounding competition, market concentration, and long-term returns receive far less attention.
During his recent appearance on the Excess Returns Podcast, veteran investor Jeremy Grantham argued that many of today’s market dynamics resemble conditions that have historically preceded painful reversals.
Grantham’s investing philosophy has long centered on mean reversion and the tendency for periods of extreme profitability to eventually attract competition. As he explained, “History was pretty clear. Asset classes mean revert. Sectors within an asset like small versus large, they mean revert. And even companies in the end mean revert.”
That framework directly challenges the current market narrative surrounding dominant technology firms.
Over the last decade, a small number of companies have accumulated extraordinary market power, helping drive margins and valuations far above historical norms.
Grantham argued much of this was enabled by a regulatory environment that tolerated growing concentration. “Companies were able to to quickly develop not just domestic monopolies but global monopolies.”
But he believes the rise of AI may ultimately intensify competition rather than cement permanent dominance.
“We have gone from a monopoly world to a brutal competitive world and we will stay there for years and there will be blood in the streets because these are aggressive take no prisoner type companies with lots of money and they are heading right into each other’s teeth.”
The enthusiasm surrounding AI has fueled enormous capital expenditures across the technology sector, with investors increasingly assuming that these investments will permanently raise corporate profitability.
Grantham strongly pushed back against that assumption by comparing AI adoption to previous technological revolutions. “When the smoke clears, any new technology is merely a cost of doing business.”
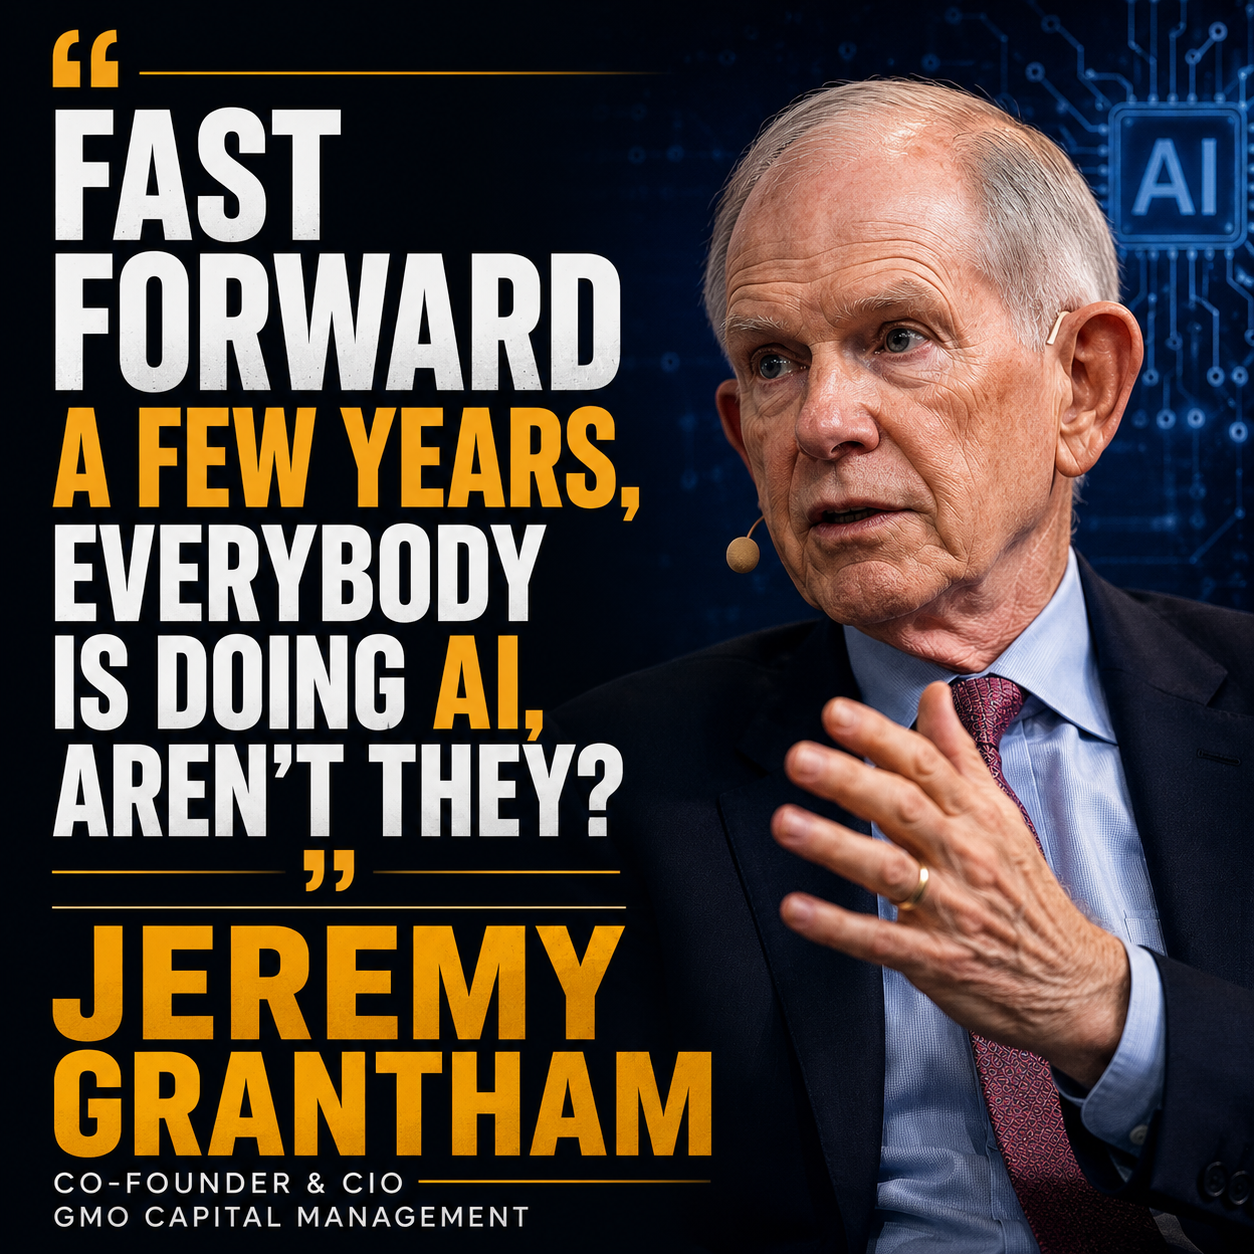
He expanded further: “Fast forward a few years, everybody is doing AI, aren’t they? Everybody is paying for the service that they need. It is now in that point in the future the cost of doing business. It will not move aggregate profit margins or aggregate profits notably higher than they are typically.”
Grantham also revisited his long-held views on bubbles, emphasizing how periods of optimism and abundant liquidity repeatedly create extreme market behavior. “A bubble occurs typically when economic conditions are nearly perfect and there’s plenty of money around.”
While Grantham acknowledged the difficulty of timing market reversals, his broader concern remains investor behavior itself.
He argued that markets consistently underestimate risk during periods of euphoria because people naturally prefer optimistic narratives over uncomfortable long-term realities.
“So as a species we do not do unpleasant news and we do not do long-term and my advice to the investor is try and fight those two tendencies.”
As AI optimism, capex races, and concentrated market leadership continue driving sentiment, Grantham’s warning is ultimately rooted in history: periods of extreme profitability, market concentration, and speculative enthusiasm rarely remain permanent, even when they temporarily appear unstoppable.
Full interview here:
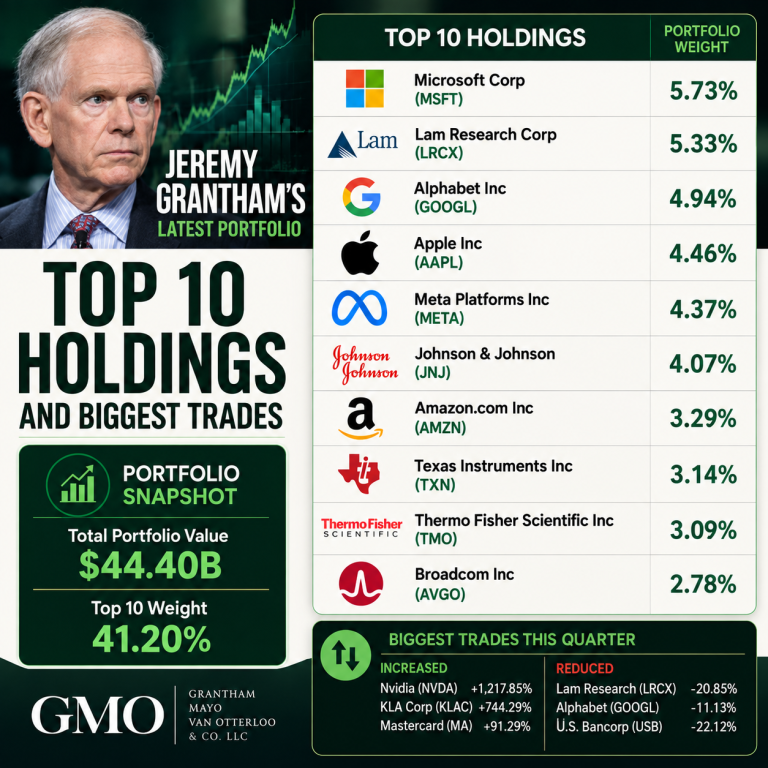 Jeremy Grantham’s Latest Portfolio: Top 10 Holdings & Biggest Trades
 Where Are the Highest-Quality Value Opportunities This Week?
 AI Spending Boom: Are Big Tech Companies Taking on Too Much Debt?