
David Abram’s Abrams Capital Portfolio: Biggest Buys, Sells, And Top Holdings Revealed
Sunday, May 31, 2026 · Johnny Hopkins
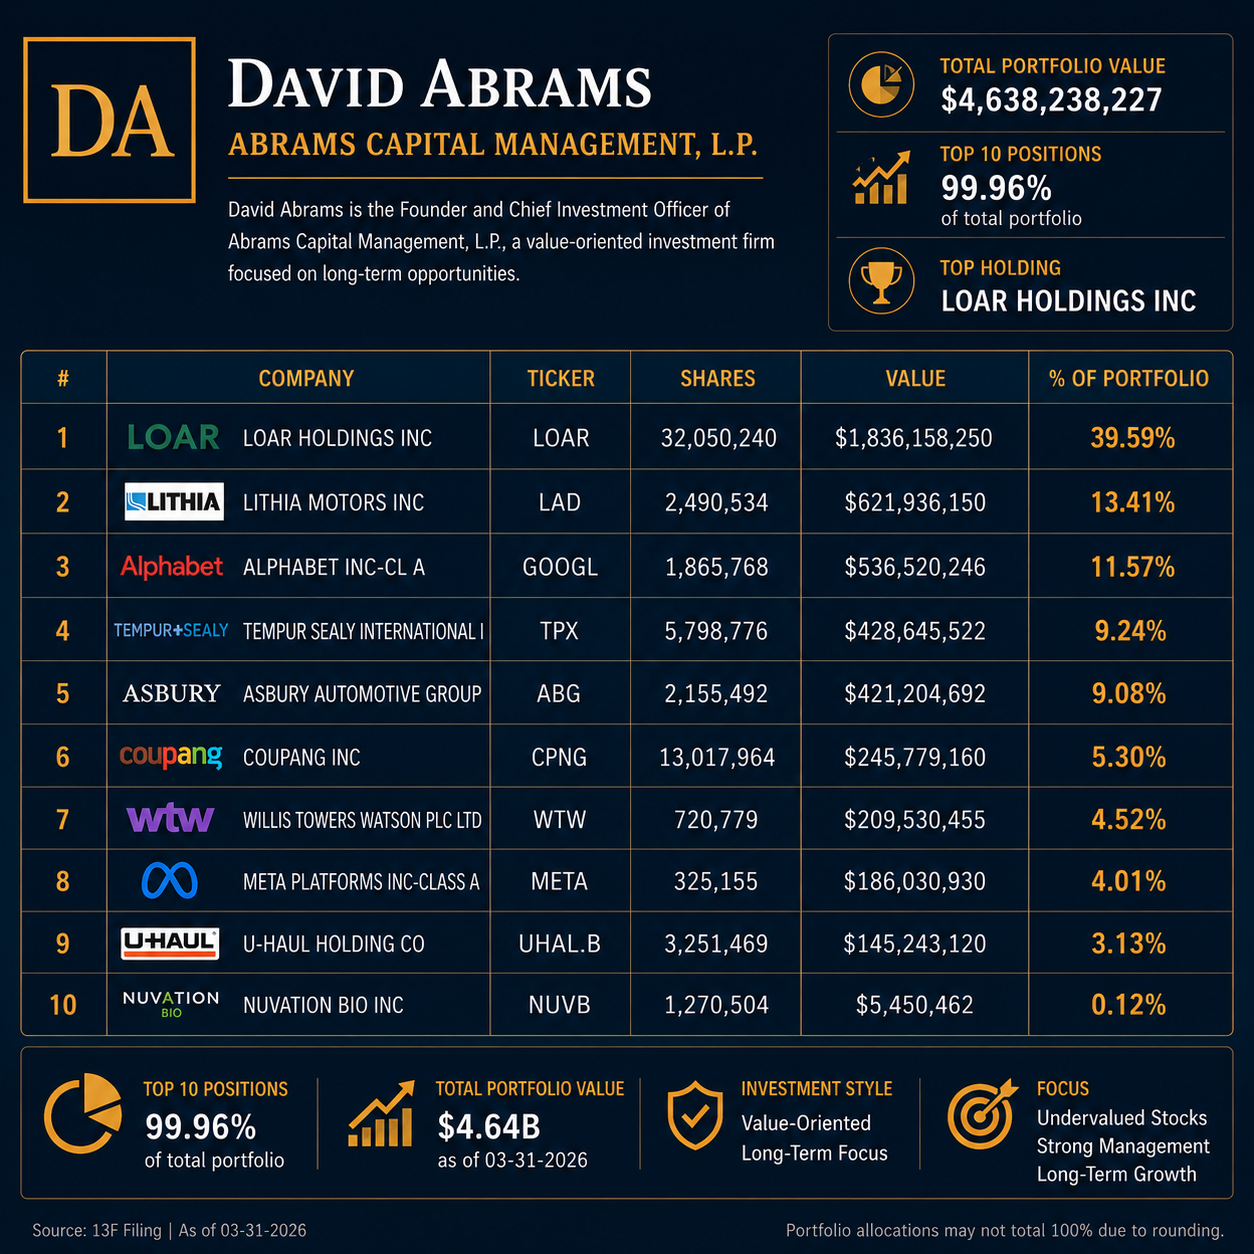
ABRAMS CAPITAL MANAGEMENT, L.P. reported an equity portfolio valued at approximately $4.64 billion in the latest reported quarter, reflecting David Abrams’ highly concentrated, long-term oriented investment approach.
Consistent with Abrams’ reputation as a focused value investor influenced by the Buffett tradition, the portfolio remains centered around a small number of high-conviction positions with significant weighting in select businesses viewed as trading below intrinsic value.
The portfolio is exceptionally concentrated, with the top 10 holdings accounting for approximately 99.96% of total assets. Activity during the quarter remained relatively limited, with only a small number of notable share adjustments while most core positions were largely maintained.
Portfolio Snapshot
Total Portfolio Value: ~$4.64B
Top 10 Weight: 99.96% (extremely concentrated)
Turnover: Very Low — minimal changes across core long-term holdings
Top Holdings & Weights
LOAR Holdings (LOAR) — ~$1.84B (39.59%)
Lithia Motors (LAD) — ~$622.0M (13.41%)
Alphabet Class A (GOOGL) — ~$536.5M (11.57%)
Tempur Sealy International (TPX) — ~$428.6M (9.24%)
Asbury Automotive Group (ABG) — ~$421.2M (9.08%)
Coupang (CPNG) — ~$245.8M (5.30%)
Willis Towers Watson (WTW) — ~$209.5M (4.52%)
Meta Platforms (META) — ~$186.0M (4.01%)
U-Haul Holding Class B (UHAL.B) — ~$145.2M (3.13%)
Nuvation Bio (NUVB) — ~$5.4M (0.12%)
Key Takeaways
Abrams Capital’s portfolio continues to reflect an unusually concentrated investment strategy built around a limited number of high-conviction positions. LOAR Holdings alone accounts for nearly 40% of reported assets, highlighting Abrams’ willingness to allow a small number of investments to dominate overall portfolio exposure when conviction is high.
The portfolio maintains meaningful exposure to consumer and automotive-related businesses through positions such as Lithia Motors, Asbury Automotive Group, Tempur Sealy, and U-Haul.
These holdings suggest continued confidence in durable consumer demand, operational execution, and long-term earnings power despite broader macroeconomic uncertainty.
Technology exposure remains concentrated in a handful of dominant platform businesses including Alphabet and Meta Platforms, both of which continue generating substantial free cash flow and maintaining leading competitive positions within digital advertising and AI infrastructure.
Biggest Changes Last Quarter
Nuvation Bio (NUVB)
Shares reduced by -2.54M (-66.67%)
→ Abrams materially reduced the Nuvation Bio position during the quarter, potentially reflecting risk management, capital reallocation, or changing conviction following prior gains or evolving clinical developments.
Alphabet Class A (GOOGL)
Shares reduced by -50,862 (-2.65%)
→ The reduction in Alphabet was relatively modest and likely reflects routine portfolio management rather than a major shift in long-term conviction.
Tempur Sealy International (TPX)
Shares reduced by -5,360 (-0.09%)
→ The Tempur Sealy adjustment was minimal, suggesting Abrams continues to maintain a high level of confidence in the company’s long-term earnings and cash flow profile.
Full Exits Last Quarter Included
Energy Transfer LP (ET)
→ Abrams fully exited Energy Transfer during the quarter, closing a position that previously represented approximately 1.78% of portfolio assets. The exit may reflect valuation discipline, capital reallocation toward higher-conviction opportunities, or changing expectations surrounding energy infrastructure returns.
Summary
Abrams Capital Management’s latest filing continues to reflect David Abrams’ disciplined, concentrated value investing philosophy centered around long-duration ownership of a relatively small number of businesses believed to be trading below intrinsic value.
The portfolio remains heavily concentrated across a handful of core positions, with limited turnover and selective adjustments reinforcing Abrams’ patient, conviction-driven approach to capital allocation.