
Why David Einhorn Is Reducing Equity Exposure Despite Solid Returns
Tuesday, March 10, 2026 · Johnny Hopkins
Greenlight Capital’s latest earnings call offered a window into how David Einhorn is positioning capital amid elevated valuations and shifting opportunities. Performance from the firm’s Solasglas strategy remains a central component of the story. As Einhorn explained, “The Solasglas Fund returned 7.9% in the fourth quarter.” He added, “The long portfolio contributed 1.4%.” Einhorn also noted that “The short portfolio contributed 4.6%, and macro contributed 3.1%.”
Those returns came during a period when major benchmarks also moved higher. “During the quarter, the 500 index advanced 2.7%,” Einhorn said.
For the full year, the comparison was more difficult. “The Solasglas Fund returned 7.5% in 2025 compared to a 17.9% return for the 500.”
Still, early results for the current year have been stronger. As Einhorn put it, “Solasglas returned 3.4% in January and 6.3% in February, bringing the 2026 year-to-date return to 9.8%.”
Despite those gains, Einhorn signaled caution about the broader equity environment. “We continue to be concerned about the equity market valuations in the U.S. and believe that in the long term, this is not a great time to have a lot of equity exposure.”
That concern is reflected in portfolio positioning. “Net exposure in the investment portfolio was approximately 29% at February, down from about 40% at year end.”
Alongside investment results, the insurance platform continues to play an important role in Greenlight Capital Re’s strategy. Einhorn emphasized the performance of the underwriting side, saying, “Greg, Tom, and the team have done a fantastic job with the underwriting portfolio while continuing our disciplined approach to risk taking.” He added, “I believe this is a key factor that led to our upgrade from AM Best from A- to A in November.”
Even with operational progress, Einhorn suggested the market may be undervaluing the company. “While Greenlight Capital Re, Ltd. is performing well and earning its cost of capital, I believe our share price does not reflect this.”
That perception has implications for capital allocation. “We believe that the company has the financial flexibility and capital strength, as exemplified by the rating upgrade, to be more aggressive on share repurchases to capture the discount being offered in the market.”
On the investment side, Einhorn also addressed questions about the rise of private credit. His response made clear that the firm’s strategy remains rooted in liquid markets.
“In terms of the asset side of our business, we do not have any private credit. We are public market investors and almost everything in the portfolio is public and able to mark to market on a quoted price.”
Why David Einhorn Is Reducing Equity Exposure Despite Solid ReturnsHe added that “the broader concern that you are suggesting relating to private credit is, you know, fundamentally peripheral to our investment strategy, and I do not expect it to have much impact one way or another on what we are doing.”
Taken together, the remarks highlight a disciplined stance: maintain selective exposure, keep liquidity high, and take advantage of valuation gaps where they appear.
Full transcript here:
Greenlight Re (GLRE) Earnings Call Transcript (Globe & Mail)
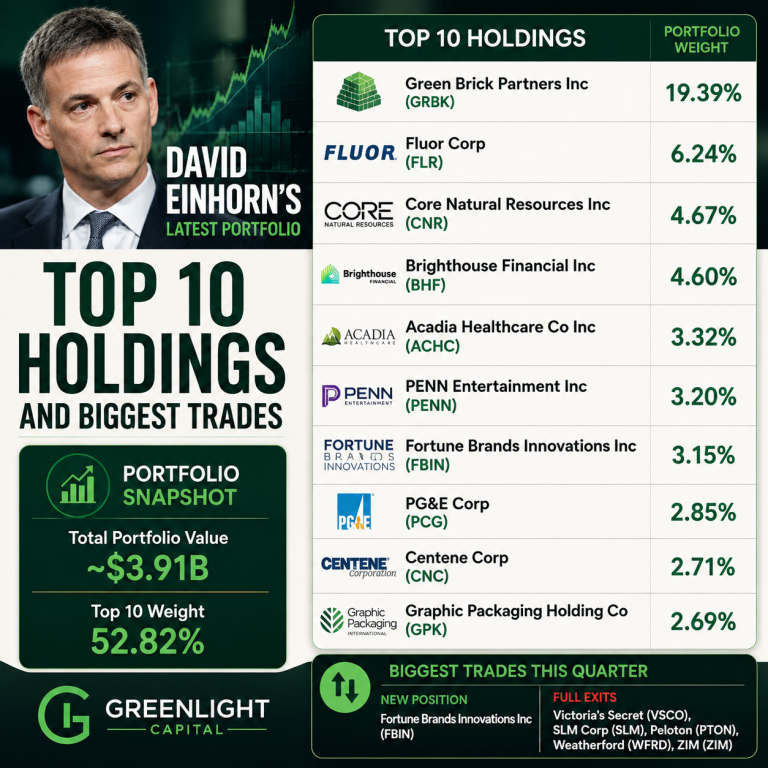 David Einhorn’s Latest Portfolio: Top 10 Holdings and Biggest Trades
 Where Are the Highest-Quality Value Opportunities This Week?
 AI Spending Boom: Are Big Tech Companies Taking on Too Much Debt?