
Rich Pzena on Value Investing Discipline After 30 Years
Sunday, February 15, 2026 · Johnny Hopkins
Value investors often search for clarity in philosophy, and in the recent presentation – Pzena’s lessons from 30 years of value investing, Rich Pzena has long framed his approach in practical rather than theoretical terms. Reflecting on the start of his firm, he explained, “Well, I mean, the reality is it was a dream. You don’t grow up thinking you’re going to start an investment firm, but over the course of my childhood and family dynamics, the idea of wanting to be in my own business was always a dream.”
That origin story still shapes how he talks about discipline, culture, and portfolio construction today, reinforcing a belief that consistency matters more than short-term popularity.
At the core of his investing stance is a straightforward description that resists unnecessary complexity. As he put it, “The investment philosophy was always very straightforward… we buy good businesses for low prices.”
Yet he quickly acknowledges the tension embedded in that idea: “The problem with that thought is that good businesses generally don’t sell for low prices.”
That contradiction drives much of value investing — searching where expectations have collapsed but underlying economics may still be intact.
Pzena frequently emphasizes that downturns create opportunity when analysis separates temporary disruption from permanent impairment.
He summarized the process bluntly: “The reality is that there are good businesses that run into difficulties and people question whether they’re good businesses when they experience some kind of a problem.”
This perspective directs attention toward firms with long operating records whose share prices have diverged sharply from historical norms, often creating asymmetric potential returns if recovery occurs.
Experience, however, refined his selectivity. Looking back, he acknowledged, “I would have said 30 years ago I would buy anything if it was cheap. Today, I would say I’m a little more selective about what I buy—but it still has to be cheap.”
Balance sheet durability has also moved higher on the checklist after difficult episodes involving leverage and creditor pressure.
Periods of underperformance inevitably test conviction. Recalling the late-1990s boom, he described the strain candidly: “We went back into the red after, you know—we had this fairy tale beginning… because we were losing clients in a world where people were going somewhere else.”
Maintaining discipline during those stretches became central to the firm’s identity.
Misconceptions about value investing remain persistent. Pzena pushes back strongly on the idea that it simply means buying troubled enterprises.
“I think the big—the single biggest misconception is that value investing is distressed investing,” he said, stressing the need to distinguish between stress and true distress. He also rejects purely quantitative shortcuts, noting, “Value is is not a factor. It’s a philosophy. And it’s the way you think about investing.”
The throughline in his comments is patience combined with valuation discipline. Market cycles shift, narratives change, and sentiment swings, but the emphasis on buying durable businesses at attractive prices continues to define his approach.
You can read the transcript from the entire presentation here:
Pzena’s lessons from 30 years of value investing (livewiremarkets)
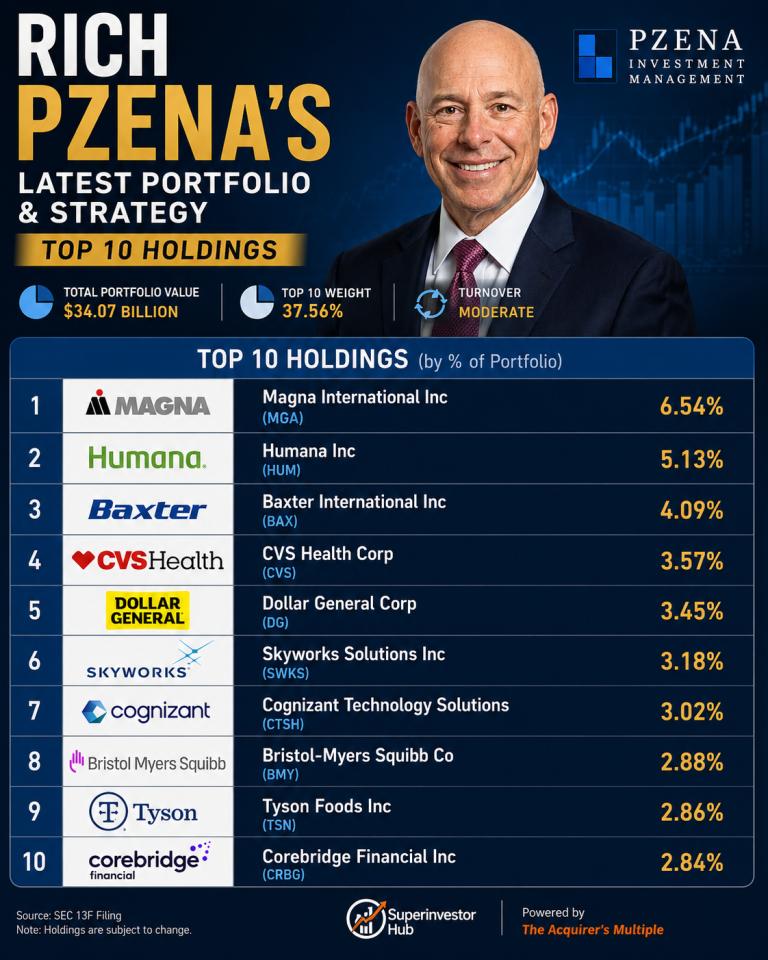 Rich Pzena’s Latest Portfolio: Top 10 Holdings & Biggest Moves
 AI Stock Market Bubble: Can the Technology Succeed While Stocks Crash?
 Closed-End Fund Investing: Buying Assets Below Net Asset Value