
Pzena: Is Extreme Momentum Setting The Stage for Value Investors?
Monday, February 2, 2026 · Johnny Hopkins
Momentum dominated equity markets in 2025, and the scale of that dominance matters for investors thinking about what comes next. As Rich Pzena’s firm, Pzena Investment Management, notes in its latest Q4 2025 commentary, “Stock price momentum was the defining force across global equity markets in 2025, marking the second consecutive year of momentum leadership in the U.S. and a similarly strong outcome outside the U.S.”
The numbers behind that statement are striking, but the underlying behavior driving returns is even more important.
According to the commentary, “Momentum stocks have outperformed by roughly 17 percentage points in U.S. and 22 percentage points in non-U.S. developed markets.”
That type of dispersion is rare, and history suggests it often coincides with later stages of a momentum cycle.
Pzena observes that “Measured over the last twelve months, momentum’s outperformance versus the market sits at historically extreme levels in both the U.S. and non-U.S. developed markets.”
Extremes do not resolve themselves immediately, but they do tend to reshape future opportunity.
One reason this period feels different is the shift in what has been leading. After an early drawdown, “That drawdown proved temporary, as momentum rebounded sharply throughout the remainder of the year.”
Since then, however, “Performance has increasingly been driven by sentiment rather than fundamentals.” The commentary highlights that this has included areas of the market that historically signal speculation rather than durable growth.
Pzena is careful to separate style definitions from outcomes. “Momentum and value are not opposites, nor are they inherently complementary.”
Over long periods, both have delivered similar average returns, but “The difference has always been timing.” The most difficult stretches for value investors have often occurred “when returns become increasingly driven by speculative behavior rather than improving fundamentals.”
That description closely mirrors what has played out recently in the U.S.
Valuation data reinforce the point. “During high-momentum periods, cheap stocks have historically lagged, while expensive stocks have generated the highest alpha.”
Yet the firm emphasizes what typically follows: “After periods of extreme and speculative momentum, forward returns have historically shifted considerably.”
In past cycles, cheaper stocks have gone on to outperform meaningfully over longer horizons as expectations reset.
Outside the U.S., the experience has been less concentrated. “Leadership in non-U.S. developed markets has historically been broader, with value stocks participating more meaningfully even during momentum-led advances.”
That broader participation has limited the degree of speculative excess seen elsewhere and helps explain why outcomes have differed by region.
The setup today reflects that history. “Momentum delivered exceptional returns in 2025, particularly in developed markets.”
At the same time, “valuation spreads have widened, and many high-quality companies have been left behind.”
For investors focused on fundamentals, Pzena concludes that “History suggests that periods of extreme momentum have often set the stage for strong long-term outcomes for patient, research-driven value investors.”
You can find the entire commentary here:
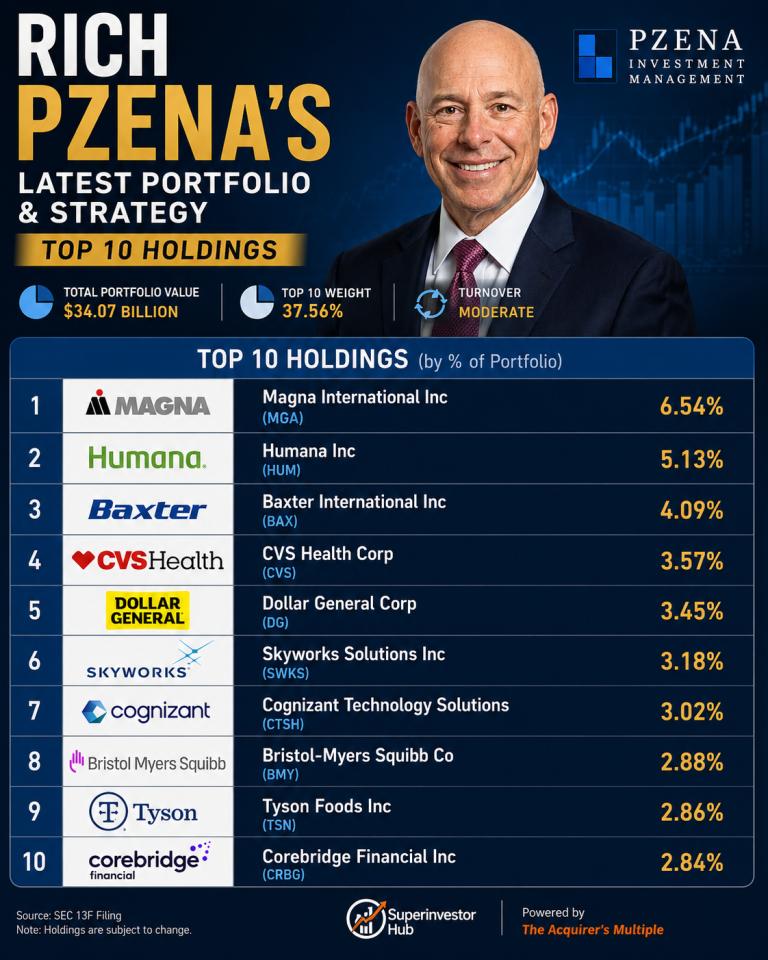 Rich Pzena’s Latest Portfolio: Top 10 Holdings & Biggest Moves
 Where Is the Deep Value in Small and Micro Caps This Week?
 AI Stock Market Bubble: Can the Technology Succeed While Stocks Crash?