
Prem Watsa: Positioning Through Deep Value & Optionality
Sunday, January 25, 2026 · Johnny Hopkins
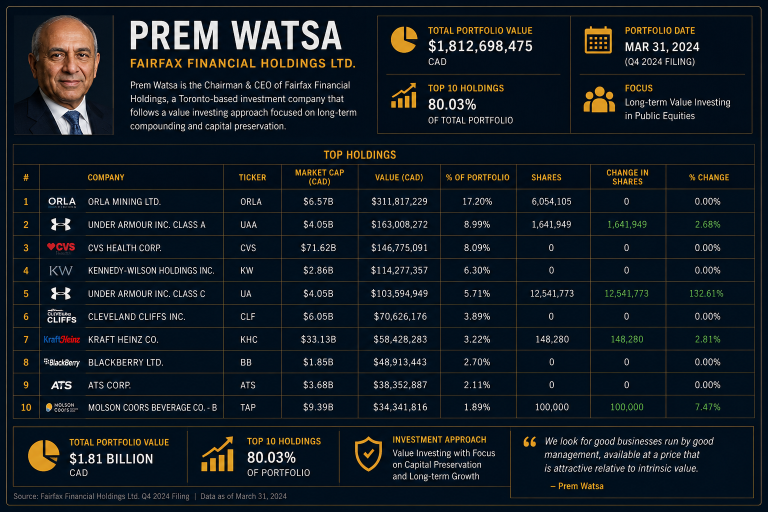
The latest 13F from Fairfax Financial reflects a steady, high-conviction allocation toward real assets, energy, and restructuring platforms — with minimal turnover during the quarter. The portfolio remains concentrated in long-duration value exposures where Fairfax believes intrinsic value exceeds market pricing. Activity this quarter was modest, signaling portfolio satisfaction rather than tactical repositioning.
1. Orla Mining (ORLA) — No Change
56.8M shares — $610.5M position (~29.6% of portfolio)
Change Shares: 0 | % Change: 0%
Orla remains Fairfax’s largest disclosed equity position. Maintaining the stake through commodity volatility suggests conviction in asset durability and intrinsic value. Exposure provides inflation hedging and long-duration optionality — a structural Watsa hallmark.
2. Occidental Petroleum (OXY) — No Change
6.05M shares — $285.9M position (~13.9%)
OXY continues as a core energy pillar. No adjustments were made this quarter, implying satisfaction with current risk/reward dynamics as Occidental continues deleveraging and capital return initiatives.
3. BlackBerry (BB) — −5,389,380 shares (Trim)
35.4M shares — $172.3M position (~8.4%)
% Change: −13.2%
BlackBerry saw the largest trim of the period. Fairfax remains a substantial holder, but the reduction reflects pragmatic de-risking as the company continues its long restructuring path. This was not a thesis exit — simply position sizing discipline.
4. Kraft Heinz (KHC) — +235,000 shares (Add)
5.12M shares — $133.2M position (~6.5%)
% Change: +4.8%
A modest consumer staple add, consistent with Fairfax’s pattern of accumulating brand-anchored cash flow at discounted valuations. KHC provides margin recapture potential and defensive ballast.
5. Molson Coors (TAP) — +71,571 shares (Add)
1.29M shares — $58.4M position (~2.8%)
% Change: +5.9%
Another measured increase in branded consumer franchises. Fairfax appears to favor staples with pricing power and normalized post-pandemic demand curves.
6. Vanguard S&P 500 ETF (VOO) — −14,652 shares (Trim)
58,248 shares — $35.7M position (~1.7%)
% Change: −20.1%
Fairfax continued scaling down passive index exposure — consistent with Watsa’s view that passive beta is less attractive relative to idiosyncratic value and hard-asset inflation hedges.
7. Helmrich & Payne (HP) — +200,000 shares (Add)
1.17M shares — $25.9M position (~1.3%)
% Change: +20.5%
One of the largest percentage adds of the quarter. HP extends Fairfax’s broader energy-services exposure — a thematic bet on upstream capital discipline and rig cycle normalization.
8. Full Exits — Autohome (ATHM) & Lifeway Foods (LWAY)
Both positions were fully exited. These were small tactical consumer holdings with low portfolio weight. Clearing them reflects continued cleanup of non-core tail positions.
Portfolio Themes
Low Turnover = High Conviction
Portfolio stability suggests Watsa already positioned for his macro regime last year.
Hard Asset & Energy Bias
ORLA, OXY, and HP reflect inflation hedging and real asset valuation preference.
Restructuring Optionality
BB remains a multi-year operational value unlock rather than a growth bet.
Cash Flow Defensives
KHC and TAP provide income stability and margin recovery potential.
Takeaway
Watsa remains committed to value + optionality rather than momentum or AI narratives. The 13F continues to express a contrarian macro stance through:
✓ hard assets
✓ energy services
✓ restructuring
✓ cash-flow consumers
A portfolio built for intrinsic value realization rather than beta capture.
 Prem Watsa’s Latest Stock Portfolio: Fairfax’s Biggest Buys and Sells
 Where Are the Highest-Quality Value Opportunities This Week?
 AI Spending Boom: Are Big Tech Companies Taking on Too Much Debt?