
GMO’s Top Holdings: Inside Jeremy Grantham’s High-Conviction Mega-Cap Portfolio
Sunday, November 30, 2025 · Johnny Hopkins
The latest 13F from Grantham, Mayo, Van Otterloo & Co. (GMO) offers a clear window into how Jeremy Grantham is positioning capital in a market he believes is both richly valued and increasingly narrow. Despite his well-known warnings about bubbles and froth, GMO’s actual equity book remains highly rational — concentrated in dominant franchises with durable cash flows, strong balance sheets, and long-term secular tailwinds.
Below is a breakdown of the most important top holdings and what they signal about GMO’s strategy.
1. Microsoft (MSFT): 4,959,599 shares — $2.57B position
Microsoft stands as GMO’s largest holding, reflecting Grantham’s focus on wide-moat compounders with predictable cash flow. Azure’s continued share gains, disciplined cost management, and early monetization of AI (Copilot, enterprise licensing) reinforce Microsoft’s positioning as the most durable mega-cap in tech.
This is a classic GMO-style anchor: low cyclicality, high returns on capital, and long-term pricing power.
2. Alphabet (GOOGL): 7,014,129 shares — $1.7B position
Alphabet is another core pillar of the portfolio. Despite trimming ~839k shares this quarter, it remains GMO’s #2 position. This reflects continued conviction in:
- Structural dominance in search
- Rising monetization from YouTube
- Improving profitability in Google Cloud
- Underappreciated free cash flow strength
The trim is consistent with GMO’s discipline: manage position sizes even when fundamentals remain intact.
3. Meta Platforms (META): 2,272,907 shares — $1.67B position
The modest increase in Meta highlights Grantham’s preference for cash-heavy franchises benefiting from secular digital advertising growth. Post-“Year of Efficiency,” Meta’s margins have expanded, Reels monetization continues to scale, and AI-driven ad tools are boosting conversion efficiency.
This remains one of the portfolio’s highest-conviction growth holdings.
4. Apple (AAPL): 6,122,841 shares — $1.56B position
Even amid slower hardware cycles, GMO maintains Apple as a core holding. Apple’s expanding Services segment, extreme buyback pace, and unmatched ecosystem stickiness preserve its compounding characteristics. The slight increase in shares shows GMO still views Apple as a high-quality, cash-generating anchor.
5. Lam Research (LRCX): 9,834,011 shares — $1.32B position
LAM stands out as GMO’s highest-conviction semiconductor pick. With AI demand driving a multiyear buildout in memory and logic equipment, LAM’s industry leadership and capital discipline make it a top beneficiary of the next leg of semiconductor investment.
GMO added ~156k shares — signaling strong belief in the cycle ahead.
Big Picture Takeaways
1. GMO is leaning heavily into cash-rich mega-cap compounders.
Microsoft, Alphabet, Meta, and Apple represent a durable, wide-moat core designed to weather volatility.
2. Selective conviction in semiconductors continues.
LAM Research is one of the purest plays on the AI infrastructure boom.
3. Grantham remains cautious on valuation — but not retreating.
The portfolio shows restraint, but also clear willingness to deploy capital into long-term, high-ROIC opportunities.
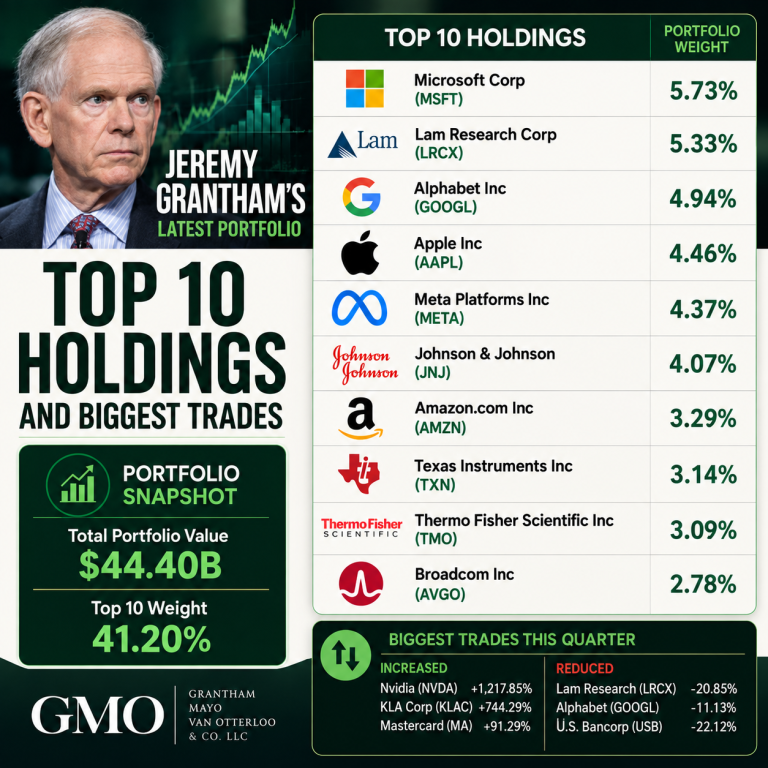 Jeremy Grantham’s Latest Portfolio: Top 10 Holdings & Biggest Trades
 Where Are the Highest-Quality Value Opportunities This Week?
 AI Spending Boom: Are Big Tech Companies Taking on Too Much Debt?