
Rich Pzena’s Top 5 Positions Represent ~21.52% Of The Total Portfolio Value
Sunday, August 10, 2025 · Johnny Hopkins
Rich Pzena’s top 5 positions represent ~21.52% of the total portfolio value of $30.75 billion. Here’s a detailed summary of the top 5 positions as of June 30, 2025, including potential reasons behind each buy or sell decision based on valuation, fundamentals, and his deep value philosophy:
Top 5 Holdings (Pzena Investment Management LLC)
1. Magna International Inc (MGA)
- Value: $1.55 billion
- Shares: 29.5 million
- Portfolio Weight: 5.05%
- Change: ▲ 1,051,882 shares (+3.70%)
Why Pzena may be buying:
Magna is a global auto parts supplier — often cyclical but highly cash-generative. Pzena likely views recent underperformance in the auto sector as a buying opportunity with margins set to rebound as electric vehicle platforms scale and global production normalizes post-COVID and chip shortages. Magna trades at a low P/E and price-to-book, fitting Pzena’s deep value discipline.
2. Cognizant Technology Solutions (CTSH)
- Value: $1.36 billion
- Shares: 17.5 million
- Portfolio Weight: 4.43%
- Change: ▲ 375,619 shares (+2.20%)
Why Pzena may be buying:
Cognizant has lagged peers like Accenture and Infosys in recent years, but Pzena may see turnaround potential under new leadership. Its legacy IT services business generates steady cash flow, and any re-acceleration in digital transformation or outsourcing could boost margins. The stock likely trades below intrinsic value, with market pessimism creating an entry point.
3. Dollar General (DG)
- Value: $1.36 billion
- Shares: 11.8 million
- Portfolio Weight: 4.41%
- Change: ▼ 921,604 shares (–7.22%)
Why Pzena may be trimming:
Dollar General has faced margin pressure from inflation and operational missteps, particularly in rural expansion. While it’s still a strong business, Pzena may be reallocating capital from DG to deeper value opportunities or locking in gains from prior purchases. The cut could also reflect concerns about near-term cost pressures or weakening consumer demand.
4. Baxter International Inc (BAX)
- Value: $1.19 billion
- Shares: 39.4 million
- Portfolio Weight: 3.87%
- Change: ▲ 2,563,919 shares (+6.97%)
Why Pzena may be buying:
Baxter’s share price fell after challenges integrating its Hillrom acquisition and spinning off its kidney care business. Pzena likely sees these temporary headwinds as overblown, with long-term fundamentals intact. Baxter’s cash flow and defensive healthcare profile fit his strategy, and a discounted valuation likely makes it attractive.
5. Citigroup Inc (C)
- Value: $1.16 billion
- Shares: 13.6 million
- Portfolio Weight: 3.76%
- Change: ▲ 242,560 shares (+1.82%)
Why Pzena may be buying:
Citigroup continues to trade at a discount to book value, making it a classic Pzena pick. Despite regulatory challenges and restructuring costs, Citi’s global footprint and capital position offer long-term value. Modest buying suggests continued conviction, with upside potential if return on equity improves.
Strategy Notes:
Rich Pzena is a deep value investor, often buying high-quality businesses during periods of temporary distress. His portfolio reflects a disciplined approach to mean reversion, favoring underperforming stocks with strong balance sheets and depressed valuations. This quarter, activity suggests a tilt toward undervalued cyclicals and turnaround plays, with cautious trimming of prior winners.
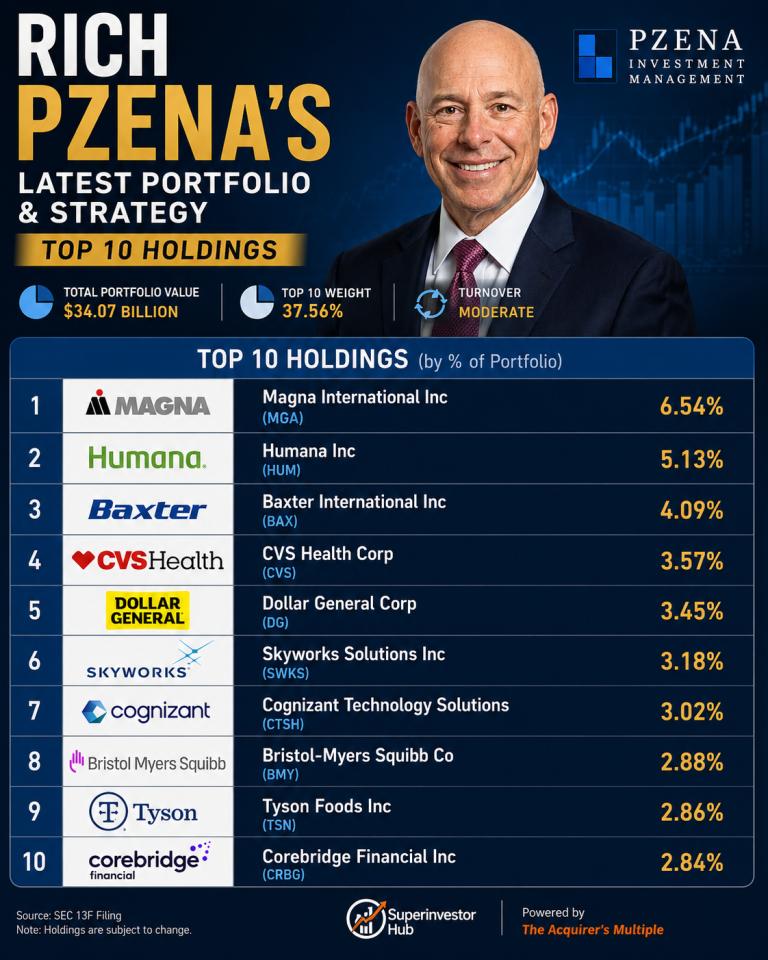 Rich Pzena’s Latest Portfolio: Top 10 Holdings & Biggest Moves
 Where Are the Highest-Quality Value Opportunities This Week?
 AI Spending Boom: Are Big Tech Companies Taking on Too Much Debt?