
Lowe’s Companies Inc (LOW): Is It a Buy? – Acquirer’s Multiple Stock Screener Analysis
Thursday, November 14, 2024 · Johnny Hopkins
As part of our ongoing series here at The Acquirer’s Multiple, each week we focus on one of the stocks from our Stock Screeners, and why it’s a ‘buy’ based on key fundamentals.
One of the cheapest stocks in our Stock Screeners is:
Lowe’s Companies Inc (LOW)
Lowe’s is the second-largest home improvement retailer in the world, operating more than 1,700 stores in the United States, after the 2023 divestiture of its Canadian locations (RONA, Lowe’s Canada, Réno-Dépôt, and Dick’s Lumber). The firm’s stores offer products and services for home decorating, maintenance, repair, and remodeling, with maintenance and repair accounting for two thirds of products sold. Lowe’s targets retail do-it-yourself (around 75% of sales) and do-it-for-me customers as well as commercial and professional business clients (around 25% of sales). We estimate Lowe’s captures a high-single-digit share of the domestic home improvement market, based on US Census data and management’s market size estimates.
A quick look at the share price history (below) over the past twelve months shows that the price is up 34.75%. Here’s why the company is undervalued.
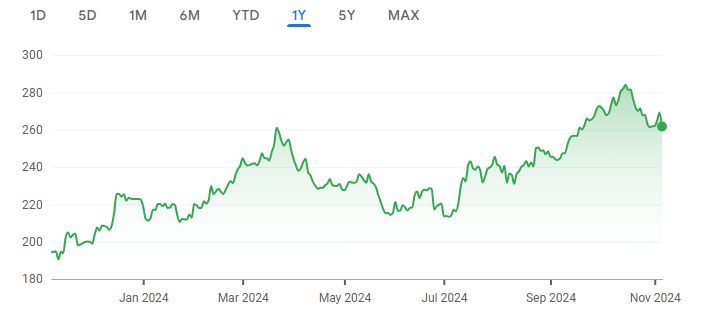
Source: Google Finance
Key Stats
Market Cap: $148.66 Billion
Enterprise Value: $184.21 Billion
Operating Earnings
Operating Earnings: $10.52 Billion
Acquirer’s Multiple
Acquirer’s Multiple: 17.50
Free Cash Flow (TTM)
Free Cash Flow: $7.58 Billion
FCF/MC Yield %:
FCF/MC Yield: 5.10
Shareholder Yield %:
Shareholder Yield: 4.10
Other Indicators
Piotroski F Score: 7.00
Buyback Yield %: 2.40
ROA (5 Year Avge%): 5
 Where Is the Deep Value in Small and Micro Caps This Week?
 AI Stock Market Bubble: Can the Technology Succeed While Stocks Crash?
 Closed-End Fund Investing: Buying Assets Below Net Asset Value